
Key takeaways
- Year-end can be a useful checkpoint to review remaining vesting events, option expiration dates, and ESPP deadlines before December 31.
- Tax withholding on equity compensation may not match your actual tax liability, so a tax projection can help you spot a potential gap.
- Company trading windows and blackout periods can limit when you are able to act, which makes planning ahead important.
- Donating appreciated shares held more than one year may be worth considering if charitable giving is part of your plans.
- Coordinating these decisions with a tax professional and your broader financial plan can help keep them aligned with your goals.
For many individuals and families, equity compensation, such as restricted stock units (RSUs), stock options, and employee stock purchase plan (ESPP) shares, can be a meaningful part of household wealth, with deadlines and tax events that don’t always align with the calendar year.
As 2026 closes, a structured review can help you see what has happened, what is coming, and which decisions may still be open before December 31. This checklist is general and educational; your plan documents, tax situation, and goals determine which items apply.
1. Map Your Remaining Vesting Events
Start with your vesting schedule from your equity plan portal.
- List any RSU or performance share vests between now and December 31, as well as those scheduled for early 2027.
- Note how shares are handled at vest. Common approaches include sell-to-cover, net share withholding, or paying taxes in cash.
- For performance-based awards, confirm with your plan administrator when shares are actually delivered.
If RSUs are a large part of your compensation, our overview of restricted stock units explains the basics in more detail.
2. Compare Withholding With Your Projected Tax Liability
Why gaps can occur
Employers often withhold on supplemental wages, including RSU income and nonqualified stock option (NSO) exercises, at a flat supplemental rate. That rate may be lower or higher than the rate that actually applies to your total income. Incentive stock option (ISO) exercises generally do not trigger regular income tax withholding, yet they may affect the alternative minimum tax (AMT). As a result, it is possible to reach tax season owing more than expected, or to have had more withheld than needed.
What to review
- Year-to-date pay and equity statements showing income recognized and taxes withheld
- Estimated tax payments already made this year
- State taxes, particularly if you moved or worked in more than one state while awards vested, since equity income may be allocated among states
A tax professional can help you estimate your liability and evaluate options such as adjusting withholding on remaining 2026 paychecks or making an estimated payment.
3. Check ESPP Enrollment and Purchase Windows
Many ESPPs have enrollment periods tied to offering periods that begin at set times of the year.
- Confirm whether an enrollment window is open or approaching, and the deadline to enroll or change your contribution rate.
- Review your contribution percentage for the next offering period in light of your cash flow needs.
- Identify any upcoming purchase dates and any shares you already hold from prior purchases.
For qualified ESPPs, selling shares before meeting certain holding periods may result in a “disqualifying disposition,” with part of the gain treated as ordinary income. Your employer should provide Form 3922 after your first transfer of ESPP shares, which reports dates and values used for tax reporting. Learn more in our employee stock purchase plan resource.
4. Review Stock Option Exercise Timing
- Check expiration dates. Options generally expire at the end of their term, or within a limited window after you leave an employer. Unexercised options can be lost after they expire.
- NSOs: The spread between the market value and the exercise price is generally taxed as ordinary income when you exercise. Exercising in December versus January can shift that income from one tax year to another.
- ISOs: Exercising generally does not create regular taxable income, but the spread may be an adjustment for AMT purposes if you hold the shares past year-end. Modeling different scenarios before December 31 can help you understand potential AMT exposure.
Our page on incentive stock options covers ISO considerations further.
5. Confirm Trading Windows and Blackout Periods
If your company has an insider trading policy, you may only be able to sell shares or exercise and sell options during open trading windows. These windows often close ahead of quarterly earnings announcements, and a closed window can overlap with the end of the year.
Check your company’s trading calendar now rather than in mid-December. If you are considering a Rule 10b5-1 trading plan, note that these plans have specific requirements, including waiting periods before trades begin; your company’s legal or compliance team can explain them.
6. Consider Charitable Giving With Appreciated Shares
If charitable giving is part of your plans, gifting appreciated shares may be an alternative to giving cash.
- According to IRS Publication 526, appreciated publicly traded stock held more than one year is generally considered capital gain property. Donating it to a qualified charity may allow a deduction based on fair market value, and you generally would not recognize the capital gain on the donated shares. Deduction limits and itemizing rules apply.
- Shares held one year or less, such as shares from a recent RSU vest, are generally treated differently, and the deduction may be limited.
- Some families use a donor-advised fund to contribute in one year and recommend grants over time.
- Transfers can take several business days, and brokers or charities may set earlier cutoff dates.
Charitable deduction rules have been subject to recent legislative changes, so it is a good idea to confirm how they apply to your 2026 return with your tax professional.
7. Other Items to Review Before December 31
- Concentration: Estimate how much of your net worth is tied to your employer’s stock, including unvested awards.
- Tax-loss harvesting: If you sell other investments at a loss, be aware that wash sale rules may apply when you acquire substantially identical shares within a set window, which can include shares received through an RSU vest or an ESPP purchase.
- Beneficiaries and estate documents: Confirm beneficiary designations are current and that your estate plan reflects how your equity awards are treated.
- Tax documents: Keep Forms W-2, 1099-B, 3921, 3922, and any supplemental plan statements.
Year-end decisions involving equity compensation can be interconnected, and it can help to look at them alongside your overall plan. If you’d like a second set of eyes on your vesting schedule, option deadlines, or giving plans, you’re welcome to request a complimentary wealth review. It’s a no-obligation conversation about your Goals, Values, and Aspirations™ and how your equity compensation fits into them.
Sources
- IRS Topic No. 427, Stock Options
- IRS Publication 525, Taxable and Nontaxable Income
- IRS Publication 526, Charitable Contributions
- IRS Topic No. 409, Capital Gains and Losses
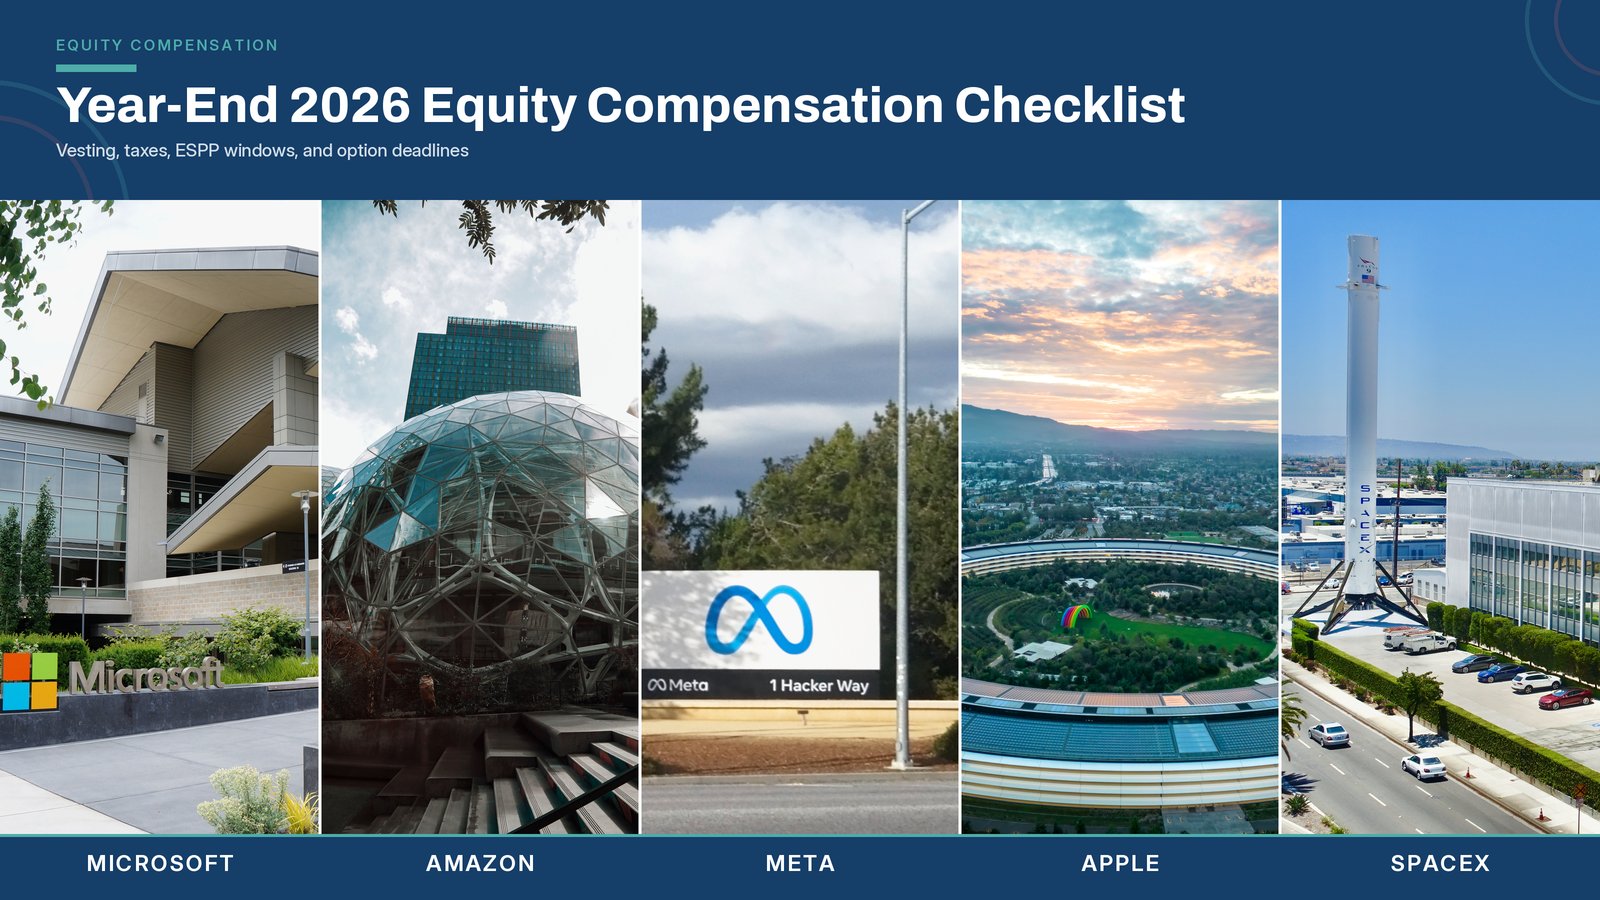
Featured image, left to right: Microsoft’s Redmond campus (Building 92), photograph by Jiaqian AirplaneFan via Wikimedia Commons, CC BY 3.0, cropped; the Amazon Spheres in Seattle, photograph by Hussein Haidar Salman via Pexels; Meta headquarters, Menlo Park, photograph by LPS.1 via Wikimedia Commons, CC0; Apple Park, Cupertino, photograph by Zetong Li via Pexels; SpaceX headquarters, Hawthorne, photograph by Steve Jurvetson via Wikimedia Commons, CC BY 2.0, cropped.
Frequently asked questions
Do I owe more tax because my RSUs vested this year?
The value of RSUs at vest is generally treated as ordinary income and reported on your Form W-2. Shares are often withheld at a flat supplemental rate, which may not cover your full liability. A tax professional can help you estimate whether you may owe more.
What happens if I don't exercise my stock options before they expire?
Generally, options not exercised by their expiration date are forfeited. Deadlines can come sooner than expected after leaving an employer.
Is it too late to donate stock for the 2026 tax year?
A gift of stock generally counts in the year the transfer is completed, so consider contacting your broker and the charity well before December 31.
Should I change my ESPP contribution at year-end?
It depends on your cash flow, goals, and existing employer stock holdings. Many plans allow changes only during enrollment windows.