
Key takeaways
- On November 12, 2026, the IRS raised the 2027 employee 401(k) deferral limit to $25,500 (up $1,000) and the total limit on all contributions to $75,000 (up $3,000).
- As of the latest plan filing that describes it (plan year 2023), Meta's match is tied to the IRS limit rather than a percentage of pay: dollar-for-dollar, up to 50% of the IRS deferral limit. Applied to 2027, that would be up to $12,750 on regular contributions.
- Meta also matches catch-up contributions, which most employers don't. That match counts toward the $75,000 total limit, so employees 50 and older generally have less after-tax room.
- In a hypothetical illustration on a $250,000 base salary, after-tax room is about $36,750 under age 50, about $32,500 at ages 50–59, and about $30,875 at ages 60–63, assuming a 50% match on catch-up.
- If your 2026 FICA wages were over $155,000 and you'll be 50 or older in 2027, your catch-up contributions generally must go in as Roth. Your plan documents control, and this isn't tax advice.
Updated for the 2027 plan year. This is general educational information based on publicly available Meta plan information and IRS guidance as of November 2026. It isn’t tax, legal, or individualized advice, and your official plan documents (the Summary Plan Description and plan document) control.
On November 12, 2026, the IRS announced the 401(k) limits for 2027 in News Release IR-2026-136. If you work at Meta (formerly Facebook), these numbers matter a little more than usual. Meta’s match has historically been tied directly to the IRS limit, and it extends to catch-up contributions. So when the IRS moves, Meta’s match ceiling may move with it.
Think of a glass with two fill lines. The lower line is what you can contribute from your paycheck. The top line is the total from every source. Whatever space is left after your contributions and Meta’s match is where after-tax savings can go. For 2027, both lines went up. Here’s what that may mean inside Meta’s plan.
What Changed for 2027
| Limit | 2026 | 2027 | Change |
|---|---|---|---|
| Your pre-tax + Roth contributions | $24,500 | $25,500 | +$1,000 |
| Age 50+ catch-up | $8,000 | $8,500 | +$500 |
| Ages 60–63 catch-up | $11,250 | $11,750 | +$500 |
| Total from all sources (the “415(c) limit”) | $72,000 | $75,000 | +$3,000 |
| 2026 wages that trigger Roth-only catch-up in 2027 | — | $155,000 | new threshold |
Source: IRS IR-2026-136 and Notice 2026-66.
One rule has a Meta-specific twist. Catch-up contributions themselves sit outside the $75,000 total. But any employer match on those catch-up dollars counts inside it. Few employers match catch-up, so this rarely matters. At Meta, it does.
Meta’s Match: Tied to the IRS Limit
Meta doesn’t publish its 401(k) formula on a public website. The most recent official description we could find is in the independent auditor’s report filed with the Meta Platforms, Inc. 401(k) Plan’s Form 5500 for the 2023 plan year. It says:
- Meta makes “a dollar-for-dollar match, up to 50% of the IRS employee deferral limit.”
- Participants are immediately vested in their entire account, including employer contributions.
- Matching contributions are described as discretionary, which means they can change.
The key idea is that Meta’s match isn’t a percentage of your salary. It’s capped at half of whatever the IRS allows you to contribute. When the IRS limit was $24,500, the cap was $12,250. With the 2027 limit at $25,500, the same formula would cap the match at $12,750. That figure is our math applying the 2023 formula to the new IRS limit, not a number Meta has published. If you contribute the full $25,500, it works out to a 50% match on what you put in.
Because the cap is tied to the IRS limit and not your pay, two Meta employees at different salaries who both contribute the full amount would generally receive the same match. That’s quite different from employers that match a percentage of pay.
Catch-Up Contributions and the Match
Here’s something that sets Meta apart: Meta matches catch-up contributions. Most large employers don’t. If you’re 50 or older, the extra $8,500 you can contribute in 2027 (or $11,750 at ages 60–63) can also earn a match.
That extra match is valuable. It also comes with a trade-off worth understanding. Your catch-up contributions sit outside the $75,000 total limit, but Meta’s match on those catch-up dollars counts inside it. Every extra match dollar uses space that after-tax contributions could otherwise fill. So for Meta employees 50 and older, a bigger match generally means less after-tax room.
How large is the catch-up match? The formula ties the match to the IRS limit. For the examples below, we assume the cap is half of your total contribution limit including catch-up. That would be 50% × $34,000 = $17,000 at ages 50–59 or 64+, and 50% × $37,250 = $18,625 at ages 60–63. Your exact amount depends on how the current plan applies the formula, so check NetBenefits or your plan summary for your figure.
Plan features can change, so please confirm your current match details in your plan’s official documents or with the plan administrator through Fidelity NetBenefits.
The After-Tax Feature at Meta
In short, a mega backdoor Roth means making after-tax contributions to a 401(k) and then converting them to Roth. For the full explanation, see how a mega backdoor Roth works.
The 2023 filing confirms that Meta’s plan accepts pre-tax, Roth, and after-tax contributions, with Fidelity as the recordkeeper. The conversion step isn’t described in that filing. Many Meta employees report an automatic Roth conversion setting in NetBenefits, but we couldn’t confirm the current setup in an official Meta document. Check NetBenefits or your plan summary for how conversions work today.
One more Meta-specific note: according to the 2023 filing, newly eligible employees are automatically enrolled at 10% of regular pay and bonuses, with 1% annual increases. Automatic enrollment applies to regular contributions only. After-tax contributions, and any conversion setting, are separate choices you make yourself.
Before you rely on these features, confirm how after-tax contributions and Roth conversions work in your plan’s official documents or with the plan administrator through Fidelity NetBenefits, since plan features can change.
How Much After-Tax Room Meta Employees May Have
After-tax room = $75,000 − your pre-tax/Roth contributions (not catch-up) − Meta’s match (including its match on catch-up)
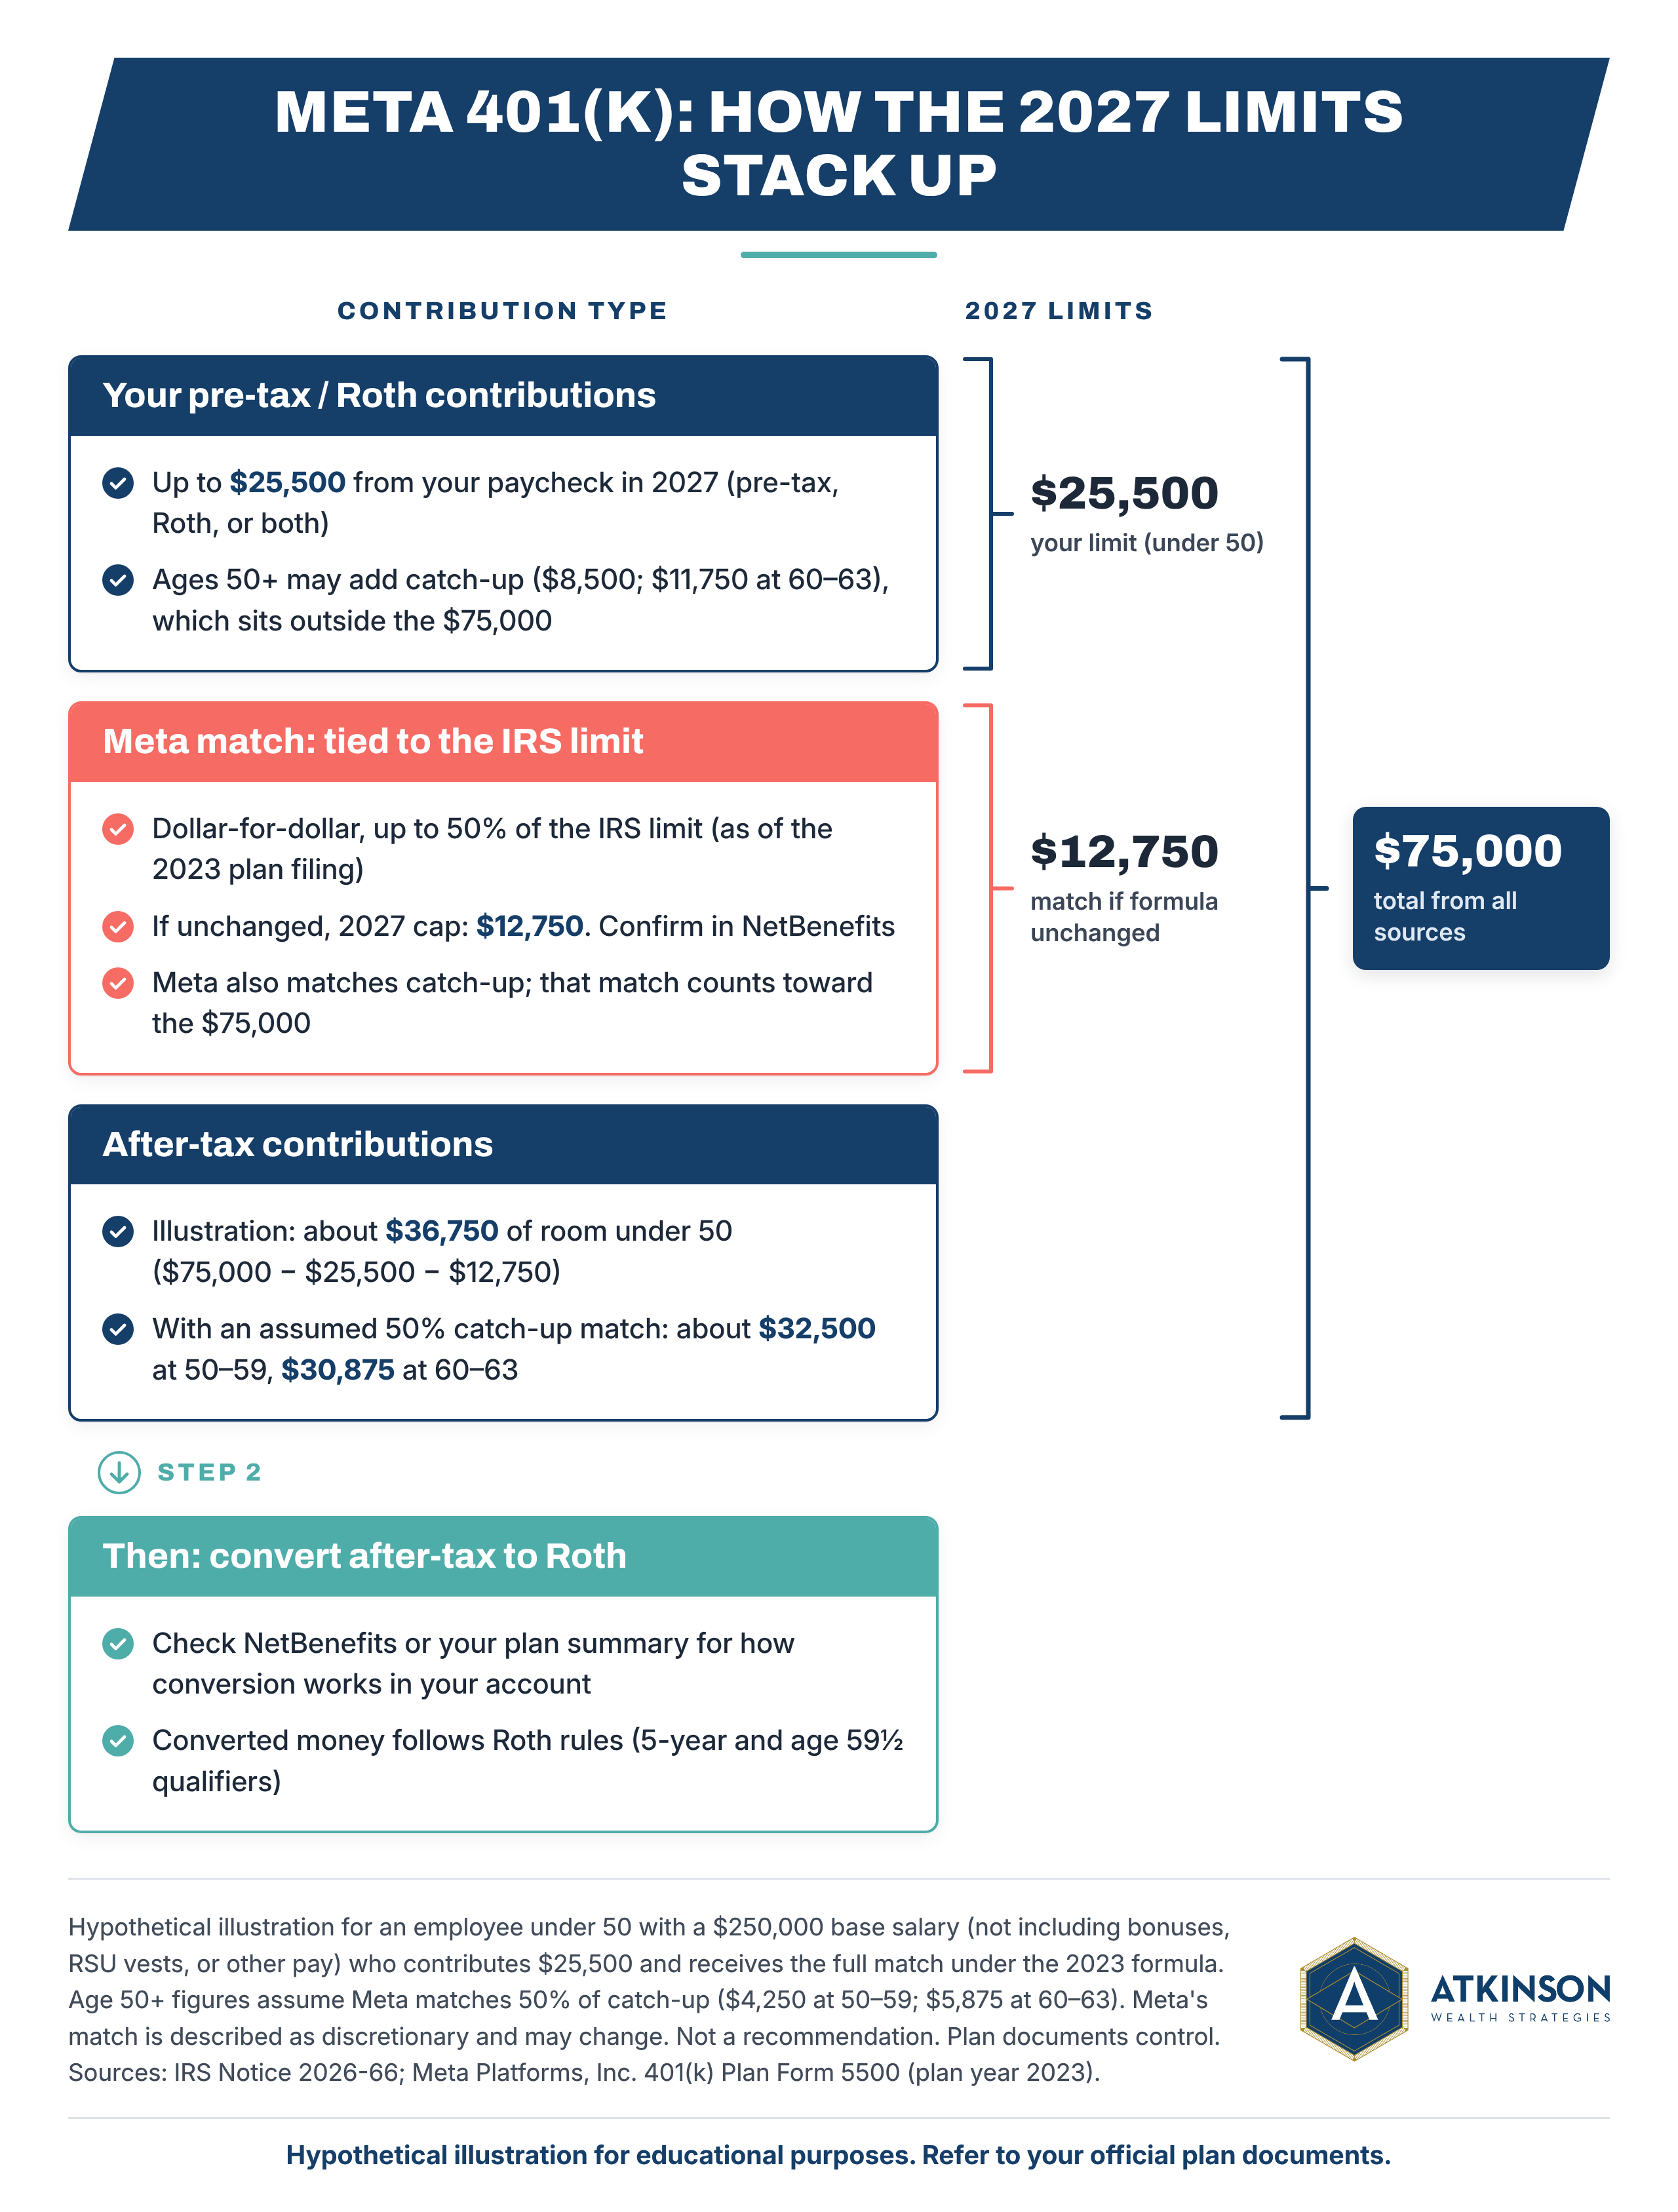
Hypothetical illustration (2027): Assume a $250,000 base salary (not including bonuses, RSU vests, or other pay), the full $25,500 plus any catch-up the employee is eligible for, the full match under the formula described above (including the catch-up assumption), no other employer contributions, no other 401(k) that year, and no limits from plan testing.
| Under 50 | 50–59 or 64+ | 60–63 | |
|---|---|---|---|
| Total limit (415(c)) | $75,000 | $75,000 | $75,000 |
| Your pre-tax/Roth contributions (not catch-up) | − $25,500 | − $25,500 | − $25,500 |
| Meta match on regular contributions | − $12,750 | − $12,750 | − $12,750 |
| Meta match on catch-up (assumed 50%) | — | − $4,250 | − $5,875 |
| Possible after-tax room | about $36,750 | about $32,500 | about $30,875 |
| Catch-up contributions (outside the $75,000) | — | + $8,500 | + $11,750 |
| Total possible savings | $75,000 | $83,500 | $86,750 |
The total that could go into the plan still rises with age, because catch-up sits on top of the $75,000. But the after-tax portion shrinks, because Meta’s match on catch-up takes up some of that space.
On a $250,000 base, $25,500 is about 10.2% of pay, and the under-50 after-tax room would be about another 14.7%. Meta’s auto-enrollment covers bonuses too, so contributions may build faster in a bonus month.
Hypothetical illustration only. It uses the stated assumptions, including a $250,000 base salary, and doesn’t reflect any actual employee. Your results will vary.
What to Think Through Before You Set 2027 Elections
Pace your after-tax contributions. Meta’s match is dollar-for-dollar until it reaches its cap, so you may reach the full match early in the year. We didn’t find a published after-tax dollar cap for Meta’s plan. If your after-tax rate is high, ask Fidelity how the plan handles reaching $75,000, so your after-tax dollars don’t take space your match would otherwise use.
Cash flow and RSUs. Many Meta employees receive a large share of pay as RSUs. Some use vesting proceeds to support higher payroll contributions. Whether that fits depends on your budget, taxes, and goals. Our overview of how RSUs work covers the tax side of vesting.
The Roth catch-up rule. If you’ll be 50 or older in 2027 and your 2026 FICA wages from Meta were over $155,000, your 2027 catch-up contributions generally must go in as Roth. On a $250,000 base, that would typically apply. Meta’s match on Roth catch-up contributions is a separate employer contribution.
Conversion timing. After-tax contributions were already taxed, so converting them generally isn’t taxed again. Earnings before conversion generally are taxable. The shorter the gap between contribution and conversion, the less taxable growth builds up. Because taxes may apply to earnings when you convert, and qualified Roth withdrawals have their own requirements, it’s wise to talk with a tax professional before converting.
Roth withdrawal rules. Qualified withdrawals from a Roth 401(k) are generally tax-free. To be qualified, the Roth account must be held at least five tax years and you must be 59½ or older, disabled, or deceased. Other withdrawals may be taxable and could face a 10% additional tax on earnings.
Plan rules. After-tax and match amounts are subject to IRS testing, which may limit highly compensated employees. Plan terms can change, and the official plan documents control.
Your 2027 Meta 401(k) Checklist
- Confirm Meta’s current match formula and 2027 cap in NetBenefits or your plan summary.
- If you’re 50 or older, check your exact catch-up match and how it reduces your after-tax room.
- Check how after-tax contributions are converted to Roth in your account today.
- Look for any older after-tax balance that was never converted.
- Review whether the Roth catch-up rule applies to you.
For a wider look at your benefits, see our page on planning for Meta employees.
If you work at Meta and would like to see how the 2027 limits fit your own situation, you’re welcome to request a complimentary wealth review. It’s a no-obligation conversation about your Goals, Values, Aspirations™, and about how your 401(k) choices, including catch-up and after-tax savings, might fit with your RSUs, taxes, and the rest of your financial life.
Related reading: 2027 Microsoft 401(k) Limits: Match and Mega Backdoor Roth.
Important information. The examples in this article are hypothetical and for illustration only. IRS limits and plan rules are subject to change. The Meta name is used only to identify the employer plan discussed. Atkinson Wealth Strategies is not affiliated with, or endorsed by, Meta. Please refer to your official plan documents for the terms that apply to you.
Featured image photo: Meta headquarters entrance at 1 Hacker Way, Menlo Park, California, by LPS.1, via Wikimedia Commons, CC0 (cropped; text added).
Sources
- IRS News Release IR-2026-136, "401(k) limit increases to $25,500 for 2027, IRA limit remains $7,500" (Nov. 12, 2026)
- IRS Notice 2026-66, 2027 Amounts Relating to Retirement Plans and IRAs
- IRS, Retirement Plans FAQs on Designated Roth Accounts
- IRS, Rollovers of After-Tax Contributions in Retirement Plans
- Meta Platforms, Inc. 401(k) Plan, Form 5500 for plan year 2023, independent auditor's report (U.S. Department of Labor EFAST2 filing search)
Frequently asked questions
What is Meta's 401(k) match under the 2027 limits?
As of the latest plan filing that describes it (plan year 2023), Meta matched dollar-for-dollar up to 50% of the IRS employee deferral limit. If that formula still applies, the 2027 cap would be $12,750. Confirm the current formula in Fidelity NetBenefits or your plan summary.
Does Meta match catch-up contributions?
Yes. Meta matches catch-up contributions, which most employers don't. The match on catch-up counts toward the $75,000 total limit, so it reduces the room left for after-tax contributions. Assuming a 50% match on catch-up, that's an extra $4,250 at ages 50–59 or $5,875 at ages 60–63 in 2027. Check NetBenefits for your exact amount.
How much after-tax room might I have for a Meta mega backdoor Roth in 2027?
In a hypothetical illustration on a $250,000 base salary, $75,000 minus a $25,500 contribution minus a $12,750 match leaves about $36,750 for someone under 50. With an assumed 50% match on catch-up, the room is about $32,500 at ages 50–59 and about $30,875 at ages 60–63. Your actual room depends on your match, age, and plan rules.
If my 2026 wages were over $155,000, do my 2027 catch-up contributions have to be Roth?
Generally yes, under the SECURE 2.0 rule and IRS Notice 2026-66. The test uses prior-year FICA wages from your employer. It applies to catch-up contributions only. A tax professional can help you understand how it affects you.